When you receive a denied health insurance claim, do not assume you must accept the decision or pay the entire bill immediately. A denial may result from a coding mistake, missing information, an eligibility problem, a policy exclusion, or a disagreement about medical necessity. In many cases, you can ask the insurer to review its decision and provide documents that support coverage.
This guide explains how to appeal a denied health insurance claim in the United States. It covers the steps to take, the records to collect, the deadlines to watch, and the options available if the first appeal fails. Insurance rules vary by plan and state, so use your policy documents and denial notice as the final guide for your situation.
What an insurance claim denial means
A claim denial means the insurer has decided not to pay all or part of a submitted medical claim. The denial may apply to a service, a medication, a procedure, a hospital stay, or a particular amount of the bill. It does not always mean the treatment was unnecessary or that you have no further options. Homeowners Insurance Coverage Types: Protecting Your Structure and Personal Assets
First, determine whether the insurer denied the claim completely or only reduced the payment. A partial payment may leave you responsible for a deductible, copayment, coinsurance, or non-covered amount. A complete denial may mean the insurer paid nothing, although the explanation may still identify a correction or appeal route.
Look at the insurer’s explanation of benefits, often called an EOB. An EOB usually lists the service date, provider charge, allowed amount, insurer payment, patient responsibility, and denial or adjustment codes. It is not always a bill. Compare it with the provider’s bill before making a payment.
Common reasons claims are denied
- Eligibility problems: The insurer says your coverage was inactive on the date of service.
- Authorization issues: The plan required prior authorization, a referral, or approval before treatment.
- Medical necessity concerns: The insurer says the service did not meet its coverage criteria.
- Incorrect coding: The provider submitted an incorrect diagnosis code, procedure code, modifier, or place-of-service code.
- Out-of-network care: The service came from a provider or facility outside the plan’s network.
- Policy exclusions: The plan excludes the service or limits when it will cover it.
- Duplicate billing: The insurer believes the same service was submitted more than once.
- Missing records: The insurer needs medical notes, test results, treatment history, or other supporting information.
- Timely filing: The claim reached the insurer after the plan’s filing deadline.
- Coordination of benefits: The plan believes another insurer should pay first.
The reason code matters because the best response depends on the problem. For example, a coding error may be fixed by the provider, while a medical-necessity denial may require a letter from your treating clinician and relevant medical records.
Review the denial before starting an appeal
Do not begin by writing a long emotional letter. Begin by identifying exactly what the insurer decided and why. A clear understanding of the denial helps you choose the fastest and most effective next step.
Read the explanation of benefits and denial letter
Find the following information:
- The date the denial was issued.
- The date of the medical service or treatment.
- The name of the provider, facility, or pharmacy.
- The specific service or claim number involved.
- The stated reason for the denial.
- The policy provision, guideline, or code cited by the insurer.
- The amount the insurer denied or assigned to you.
- The deadline for filing an internal appeal.
- The address, online portal, fax number, or other submission method.
- The documents the insurer requests.
If you cannot find this information, call the member services number on your insurance card. Ask the representative to explain the denial in plain language. Write down the representative’s name or identification number, the date and time of the call, and any reference number for the conversation.
A phone call can clarify the problem, but it may not replace a formal appeal. Ask whether the issue can be corrected without an appeal. For example, the representative may tell you that the provider must resubmit a corrected claim. Request confirmation of the instructions in writing whenever possible.
Check whether the plan is employer-based, individual, government-funded, or self-funded
The type of coverage can affect the appeal process. An individual plan purchased through a Marketplace may follow different procedures from a plan provided by an employer. A self-funded employer plan may be administered by an insurance company, but the employer plan documents can control important details.
Government programs also have separate procedures. Medicare, Medicaid, and military health programs may use their own forms, levels of appeal, and deadlines. If your coverage is connected to one of these programs, use the official instructions for that program rather than relying only on a general private-insurance guide.
For employer coverage, ask the human resources department or plan administrator for the summary plan description and full plan documents. These materials may explain exclusions, appeal levels, filing deadlines, and who makes the final decision.
How to appeal a denied health insurance claim step by step
The following process works for many private health plans, although the exact forms and deadlines can differ. Keep a separate folder for the claim. Save letters, bills, medical records, portal messages, fax confirmations, and notes from phone calls.
Step 1: Confirm the appeal deadline
Find the deadline in the denial notice or plan documents. Some plans measure the deadline from the date on the denial letter. Others may use the date you received the notice or the date the claim was processed. Do not guess. Ask the insurer to identify the deadline and record the answer.
Submit the appeal early if possible. Mailing delays, portal problems, missing pages, and incorrect fax numbers can cause avoidable problems. If the deadline is close, use the insurer’s fastest accepted method and keep proof that you submitted the appeal on time.
If you missed the deadline, submit the appeal anyway and explain the reason. A serious illness, hospitalization, language barrier, disability, delayed receipt of the notice, or another circumstance may support a request for an extension. Do not assume a late appeal will automatically be rejected.
Step 2: Ask the provider to investigate
Contact the doctor’s billing office, hospital billing department, pharmacy, or other provider involved in the claim. Ask whether the provider received a claim denial and whether the submitted information was accurate.
Request that the provider check:
- Your name, birth date, member identification number, and group number.
- The insurance company and billing address.
- The service date and place of service.
- The procedure and diagnosis codes.
- Any required modifier or authorization number.
- Whether the claim was submitted within the required time.
- Whether medical records or a referral were included.
Some denials are administrative and can be resolved through a corrected claim. Ask the provider whether it should resubmit the claim rather than asking you to appeal. Get a confirmation number or a copy of the corrected claim if available.
A corrected claim and an appeal are not always the same thing. A corrected claim may fix inaccurate billing information. An appeal asks the insurer to reconsider a coverage decision. In some situations, you may need both. Prescription Drug Coverage: What Health Insurance Pays
Step 3: Request the insurer’s coverage criteria
If the denial involves medical necessity, experimental treatment, a policy exclusion, or a treatment limit, ask the insurer for the exact policy language and clinical criteria used. You may also ask for the name of the guideline or policy relied upon in the decision.
Read the criteria carefully. Compare them with your diagnosis, symptoms, treatment history, test results, and the service your clinician recommended. The appeal should address the insurer’s stated reason directly. General statements such as the treatment is important may not be enough.
Ask whether the denial was made by a medical reviewer or only through an administrative process. Also ask whether your doctor can speak with the insurer’s reviewing clinician through a peer-to-peer discussion. This conversation may help clarify missing information, but it should not replace a written appeal when one is required.
Step 4: Gather documents that support coverage
Strong appeals are organized around evidence. Include only relevant records, and label each attachment so the reviewer can find important information quickly.
Useful documents may include:
- The denial letter and explanation of benefits.
- The relevant pages of the insurance policy or plan document.
- Clinical notes from your treating provider.
- A letter of medical necessity.
- Test results, imaging reports, laboratory results, or pathology reports.
- A treatment history showing what has already been tried.
- Records showing side effects, complications, or failed alternatives.
- A prescription, referral, or prior authorization request.
- Peer-reviewed clinical information when it directly supports the request.
- Evidence of an authorization or approval already issued.
- Proof of timely submission or previous communications with the insurer.
- A corrected claim form from the provider, when applicable.
Do not send your entire medical file unless requested. Excess material can hide the facts that matter. Ask your clinician to identify the specific records that support the requested care.
Step 5: Ask your clinician for a focused letter
A medical-necessity letter should explain your condition and connect it to the requested service. It should not simply repeat that you need treatment.
Ask the clinician to address:
- Your diagnosis and relevant symptoms.
- The service, medication, device, or procedure requested.
- Why the service is appropriate for your condition.
- What could happen if treatment is delayed or withheld.
- Which treatments or alternatives you have already tried.
- Why the insurer’s preferred alternative may not be suitable.
- Relevant test findings and clinical history.
- The expected duration, frequency, or dosage of treatment.
- Any urgent health concern connected to the request.
The letter should use accurate medical details and match the records. Ask the clinician’s office to send it through the required channel or give you a copy for your appeal file.
Step 6: Write and submit the appeal
Use the insurer’s appeal form if one is required. If there is no required form, write a short cover letter and attach supporting records. Put the claim number and member identification number on every page when appropriate.
A practical appeal structure looks like this:
- Opening: State that you are appealing the denial of a specific claim or service.
- Identification: Provide your name, member number, claim number, provider, service date, and contact information.
- Decision being challenged: Describe what the insurer denied and quote or summarize the stated reason accurately.
- Why the decision should change: Explain the error, policy language, clinical facts, or missing information that supports coverage.
- Evidence list: Identify each attachment and explain its relevance.
- Requested outcome: Ask the insurer to reprocess the claim, authorize the service, pay the claim, or correct your cost-sharing responsibility.
- Closing: Ask for a written decision and provide the best way to contact you.
Use a calm and factual tone. You do not need to accuse the insurer of acting unlawfully. A precise explanation makes it easier for a reviewer to understand what went wrong.
Submit the appeal through a method the plan accepts. Depending on the plan, that may include an online member portal, mail, fax, or another method listed in the denial notice. Keep a complete copy of everything you send.
Step 7: Confirm receipt and track the response
After submitting the appeal, confirm that the insurer received it. Ask whether any pages are missing and whether the appeal is considered complete. Record the date of receipt and the expected decision date.
Mark the expected response date on your calendar. If the insurer does not respond, contact member services and ask for an update. Keep a written record of every follow-up.
Some situations may qualify for an expedited review. This may apply when waiting for the ordinary process could seriously jeopardize your health, your ability to regain maximum function, or your ability to receive needed treatment. Ask the insurer whether an expedited appeal is available and what documentation it requires. What Is an Out-of-Pocket Maximum in Health Insurance?
What to do if the first appeal is denied
A first-level denial may not be the final decision. Read the new decision letter carefully. It should explain whether another internal appeal is available and whether you can request an external review.
Request a second internal review when available
A second appeal can be useful when the first reviewer overlooked records, applied the wrong policy provision, or did not address your clinician’s explanation. Do not simply resend the first appeal. Explain what the first decision failed to consider and add new evidence if available.
Ask the insurer to identify the exact reason the denial remains in place. If the first decision says records were missing, provide those records. If it cites a coverage exclusion, explain why the exclusion does not apply or why the requested service falls within a covered benefit.
Ask about an independent external review
Many health plans offer an external review by an independent organization when a denial involves medical judgment, medical necessity, experimental treatment, or similar issues. The reviewer is separate from the insurer, although eligibility rules and procedures vary.
The denial letter should explain whether you qualify, how to request external review, and the deadline. In some cases, an external review may be available after an internal appeal. In other situations, an expedited external review may be possible.
External review is different from a regular customer-service complaint. It is a formal process with its own submission requirements. Follow the instructions carefully and include the denial decision, clinical records, policy language, and a focused explanation of why the insurer’s decision should be reversed.
Contact the appropriate regulator or assistance program
If you cannot understand the process or believe the plan is not following its stated procedures, contact the agency that regulates your coverage. For many individual and fully insured plans, the state insurance department may provide consumer assistance or explain complaint procedures. The state agency may not regulate a self-funded employer plan in the same way.
For employer-sponsored coverage, contact the plan administrator first. If the plan is subject to federal benefits rules, the U.S. Department of Labor’s Employee Benefits Security Administration may provide information about health-plan claims and appeals.
For Marketplace coverage, federal consumer resources explain internal appeals and external review rights. Medicare and Medicaid beneficiaries should use the appeal instructions for their specific program. Keep in mind that a regulator or assistance office may explain procedure without guaranteeing payment of the claim.
How to handle medical bills while an appeal is pending
Do not ignore a provider bill while waiting for the insurer’s decision. Contact the billing office and explain that the claim is under appeal. Ask whether the account can be placed on hold or whether the provider can delay collection activity while the review is pending.
Get any payment arrangement in writing. Ask whether paying a portion of the bill could affect the appeal. Also ask whether the provider will refund or reapply a payment if the insurer later covers the claim.
If the bill is large, request an itemized statement. Compare it with the EOB and look for duplicate charges, services you did not receive, incorrect dates, or amounts that do not match your plan’s explanation. A billing error can exist even when the insurer’s coverage decision is correct.
Ask the insurer how the claim will affect your deductible and out-of-pocket maximum. A denied claim may not be treated the same way as a covered claim when calculating those amounts. The answer depends on the plan and the reason for denial.
If you cannot afford the bill, ask the provider about financial assistance, an interest-free payment plan, or a reduced balance. Do this while pursuing the appeal. Seeking payment help does not necessarily mean you agree that the denial is correct, but confirm the terms before signing anything.
Common mistakes that weaken an appeal
- Missing the deadline: A strong argument may not be considered if it arrives late.
- Appealing the wrong issue: A medical explanation will not fix a simple member-number error.
- Sending no evidence: The reviewer may not have access to all relevant records.
- Using vague language: Explain exactly why the denial conflicts with the policy or medical facts.
- Ignoring the provider: The billing office may be able to correct the claim quickly.
- Submitting unorganized records: Label attachments and refer to them in the letter.
- Relying only on phone calls: Ask for important instructions and decisions in writing.
- Assuming a bill is final: Compare the bill with the EOB and investigate discrepancies.
- Overstating facts: Keep every statement accurate and consistent with the medical record.
- Sending sensitive information casually: Use the insurer’s secure portal, approved fax, or mailing process.
Also avoid sending a generic form letter without adapting it to your claim. A template can help organize your thoughts, but the strongest appeal responds to the specific denial code and policy language.
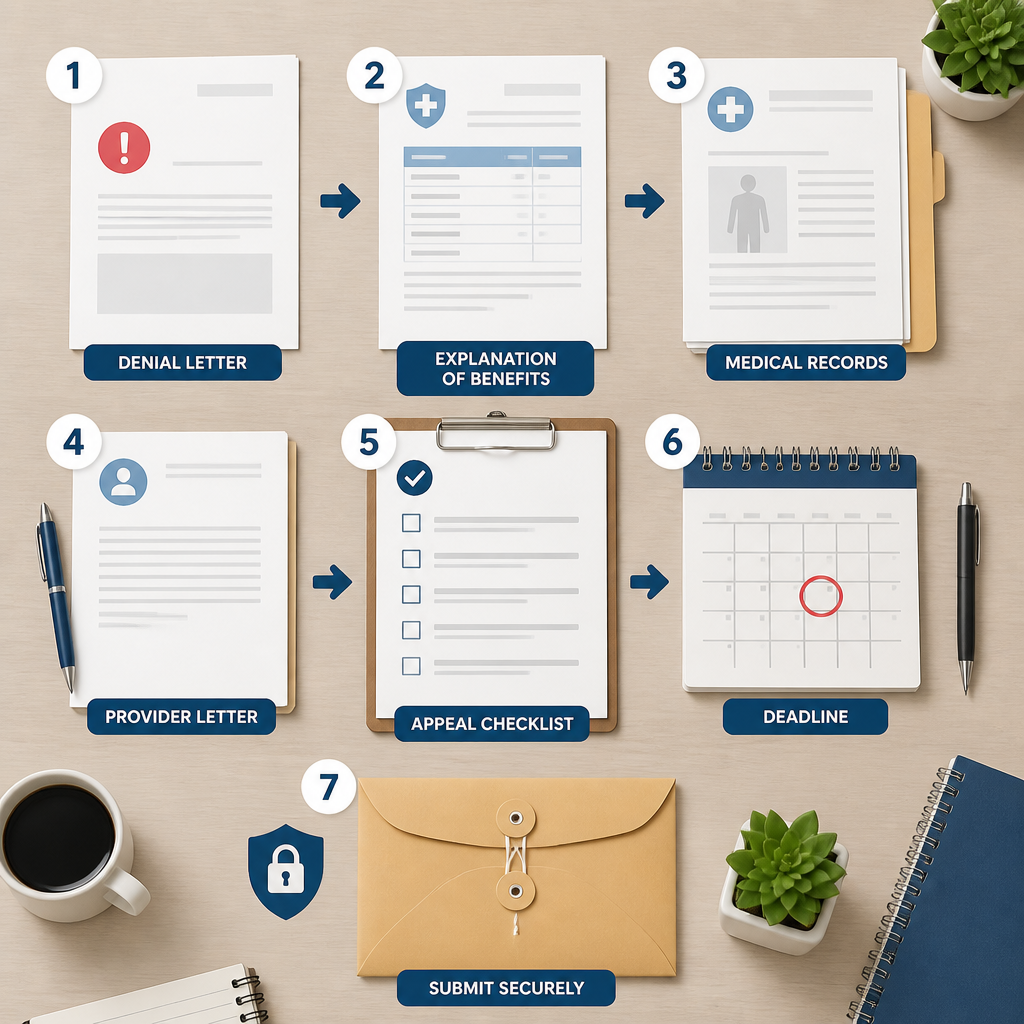
A practical denied health insurance claim checklist
Use this checklist to organize the process: How to Appeal Denied Health Claim: A Practical Guide
- Find the denial notice and explanation of benefits.
- Identify the denied service, claim number, denial reason, and appeal deadline.
- Call the insurer to clarify the decision and record the conversation.
- Ask the provider to check coding, authorization, eligibility, and timely filing.
- Determine whether the provider should submit a corrected claim.
- Request the relevant policy provision and medical-review criteria.
- Ask your clinician for records and a focused medical-necessity letter.
- Prepare a concise appeal letter with a list of attachments.
- Submit the appeal using an accepted method before the deadline.
- Keep proof of submission and confirm receipt.
- Track the decision date and follow up if necessary.
- Review options for a second appeal, external review, or regulatory assistance.
- Communicate with the provider about bills and collection activity.
When professional help may be worthwhile
Many people can handle a routine claim correction or straightforward appeal themselves. Professional help may be useful when the claim involves a large amount, urgent treatment, repeated denials, a complex policy exclusion, or a serious medical condition.
Possible sources of help include a hospital patient advocate, a nonprofit consumer assistance program, an employer benefits specialist, a licensed insurance professional, or an attorney familiar with health-plan disputes. Ask about fees, conflicts of interest, and the scope of help before sharing records or signing an agreement.
A patient advocate may help you gather documents and communicate with the insurer. An attorney may help analyze plan language, employment-benefit rules, contract issues, or litigation options. Neither can guarantee that the insurer will reverse its decision.
If your treatment is urgent, do not delay medical care solely because an insurance dispute is unresolved. Ask your clinician about safe options, emergency procedures, payment assistance, and whether the insurer can conduct an expedited review.
Frequently asked questions
Can I appeal a denied health insurance claim myself?
Yes. Most plans allow the member, an authorized representative, or sometimes the treating provider to request review. Follow the instructions in the denial notice. You may authorize a family member, advocate, or clinician to help, but do not assume another person can act for you without written permission.
Should I call the insurer before filing a written appeal?
A call can clarify the reason for the denial and reveal an easy correction. However, a call may not count as a formal appeal. If the notice provides a written appeal process, submit the required materials before the deadline even if you are also calling customer service.
What if the provider caused the error?
Ask the provider to correct and resubmit the claim. Tell the insurer that the provider is investigating the billing issue. If the deadline is approaching, ask the insurer whether a corrected claim will extend or preserve your appeal rights. Get the answer in writing.
Can I appeal a denial based on medical necessity?
Usually, medical-necessity denials can be challenged with clinical records, a detailed letter from your treating clinician, and evidence that addresses the insurer’s criteria. Explain why the requested care fits your condition and why alternatives may not be appropriate.
What if the insurer says the treatment is experimental?
Ask for the exact definition and policy provision used. Your clinician should address the treatment’s purpose, available evidence, your medical history, and why the treatment is appropriate. If available, request an external review and follow its specific documentation rules.
Can I appeal an out-of-network denial?
Possibly. Review the plan’s network rules and exceptions. Some plans may have exceptions for emergencies, unavailable in-network specialists, or certain circumstances involving access to care. Ask the insurer what documentation it requires and whether the provider’s status was listed accurately.
What happens if I win the appeal?
The insurer may reprocess the claim, issue payment to the provider, adjust your balance, authorize future care, or apply the claim to your cost-sharing amounts. Review the updated EOB and provider bill to confirm that the correction was completed.
What happens if I lose every appeal?
Ask for the final decision and the reason in writing. Check whether external review, a regulator complaint, a plan administrator review, or another program-specific appeal remains available. Also discuss billing assistance with the provider. The next step depends on your plan type, state, and the issue involved.
Final thoughts
A denied health insurance claim can feel confusing, especially when you are already dealing with illness, treatment, or an unexpected bill. The most effective response is usually organized and prompt. Start with the denial reason, confirm the deadline, involve the provider, collect targeted evidence, and address the insurer’s stated concern directly.
Keep copies of every document and record each conversation. If the first review does not resolve the problem, look for a second internal appeal, external review, plan administrator, regulator, or consumer assistance resource. A denial is a decision to challenge, not always the end of the process.